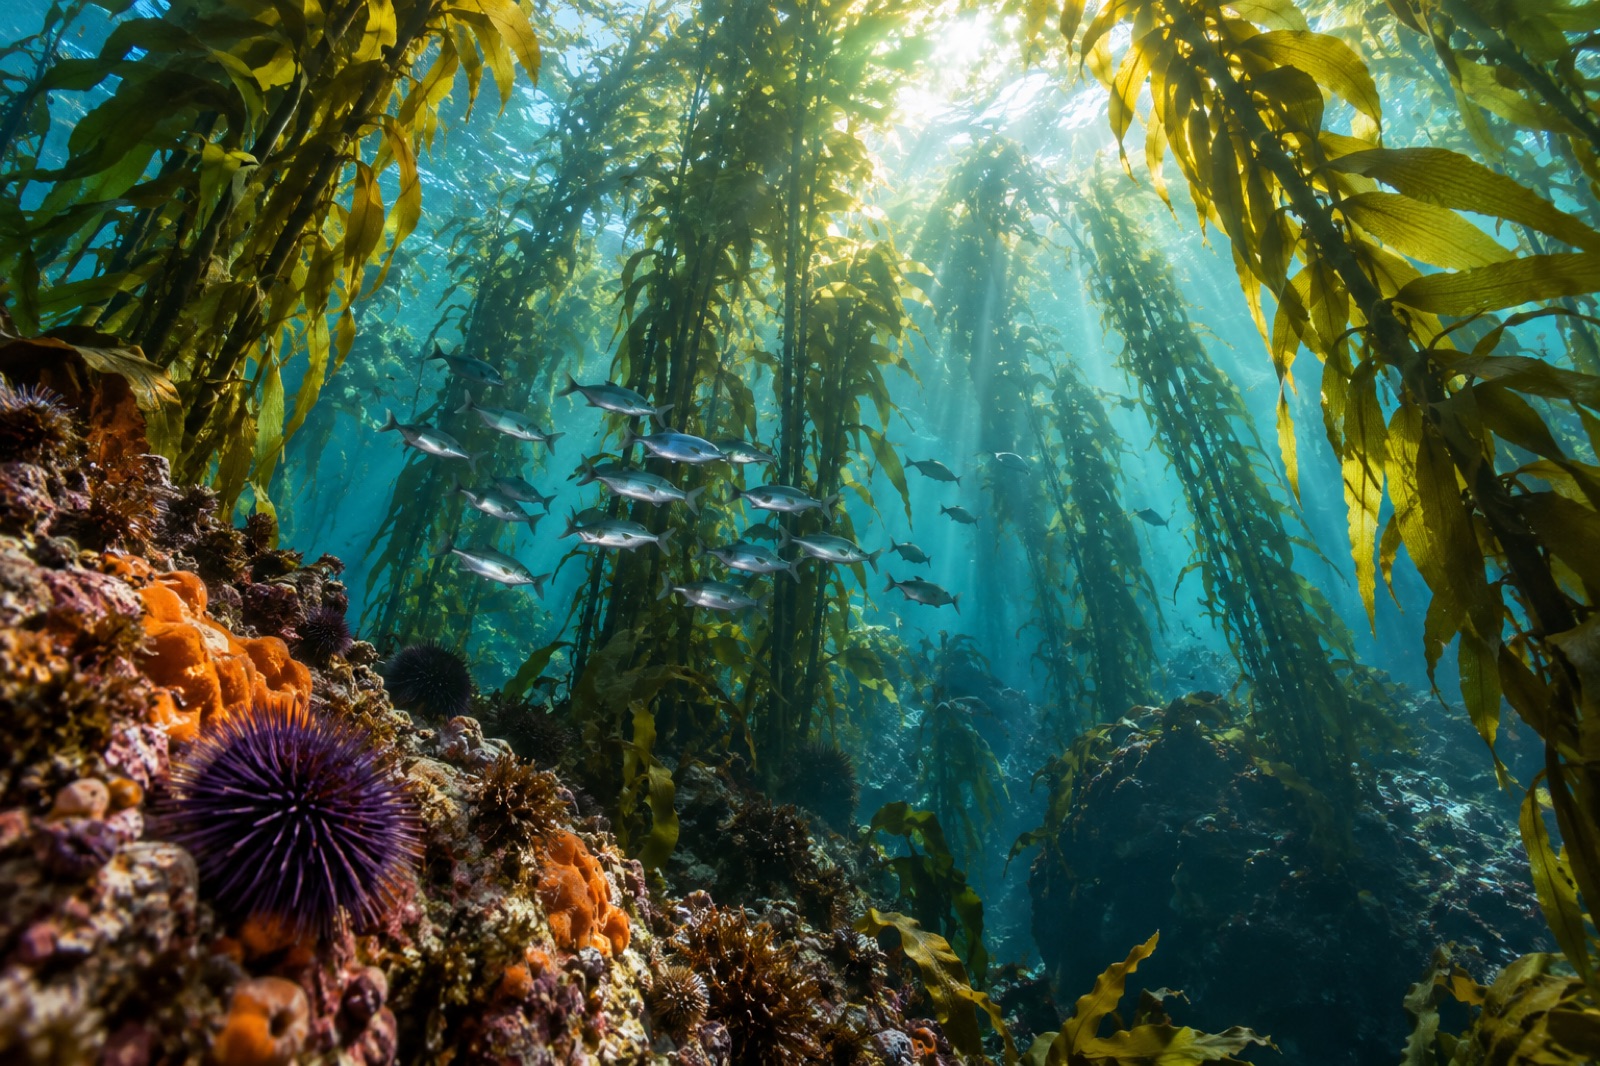
Stand at the edge of a restored kelp forest and you see one ecosystem doing two things at once. It is pulling carbon into meadow canopies and drift biomass — a climate outcome measured in tonnes. And it is sheltering abalone, garibaldi, weedy seadragons and a thousand benthic invertebrates — a biodiversity outcome measured in everything else. Carbon markets will happily pay for the first. A newer family of nature credits (also called biodiversity credits or nature certificates) is trying to be the payment rail for the second.
The two ledgers look similar — projects, standards, registries, buyer claims — but they reward different things, fail in different ways, and cannot be casually added together. This article compares them honestly: what a nature credit actually certifies, why it is harder to standardise than carbon, where stacking is legitimate and where it becomes double-dipping, and what buyers should ask before buying either.
The short version
- Carbon credits certify a quantity: one metric tonne of CO₂-equivalent removed or avoided, verified against a methodology.
- Nature credits certify an outcome: a measured improvement in ecosystem condition or species persistence, increasingly wrapped in a token-like tradable unit.
Carbon is fungible because the atmosphere does not care where a tonne comes from. Biodiversity is stubbornly place-based — a hectare restored in Tasmania is not equivalent to a hectare restored in Hokkaido — and that single fact drives most of the design tension in nature markets.
What nature credits are trying to capture
Nature credit frameworks aim to quantify and monetise outcomes like:
- Condition improvements: structural complexity, native species cover, invasive species removal.
- Species outcomes: population recovery for target species, occupancy, breeding success.
- Ecosystem function: nursery habitat provision, primary productivity, water filtration.
Most emerging schemes define a unit something like one unit = a defined uplift in measured condition over a defined area over a defined time, with monitoring recorded on a registry. The challenge is that "condition" is a composite of dozens of ecological metrics; reducing it to a stackable unit is a political and scientific choice, not a measurement. A serious nature-market standard has to make those choices transparent and justify them. Our guide to biodiversity credits goes deeper on how existing schemes define their units.
Why carbon was easier (and what that hides)
Carbon markets got a head start because the unit is physically definable — a tonne is a tonne — and globally fungible. The market did not have to ask whether a tonne "counted"; it only had to ask whose tonne it was and whether it was real.
Nature credits inherit neither luxury:
- The unit must be constructed. There is no natural metric of "one biodiversity." Schemes decide what gets counted, and different schemes answer differently.
- Fungibility is limited. A tonnage-canopy unit in a temperate kelp forest is not exchangeable for a tropical mangrove unit without a conversion logic few buyers trust. This frustrates global liquidity, but it is also ecologically honest: biodiversity is local.
- Baseline and additionality are harder. "What would this forest look like without you?" is a trickier counterfactual for species assemblages than for tonnes. Additionality debates that plague carbon branding apply here too — see Additionality in Carbon Credits.
The honest consequence: nature credit markets will likely stay smaller, more bespoke and more place-rooted than carbon markets for a long time. Many ecologists regard that as a feature.
Comparing the two ledgers, property by property
| Property |
Carbon credit |
Nature credit |
| Core unit |
1 t CO₂e removed/avoided |
Scheme-defined condition or outcome unit |
| Fungibility |
Global |
Mostly local / place-based |
| What the buyer claims |
Scopes/NET-zero contribution or contribution claim |
Nature-positive contribution; increasingly "net gain" |
| Biggest integrity risk |
Overestimation, leakage, reversal |
Metric gaming, perverse incentives, unverifiable uplift |
| Permanence basis |
Decades to centuries (with buffer pools) |
Project- or easement-defined; often ongoing stewardship |
| Overlap risk |
Double counting of tonnes |
Double-claiming of the same hectare's outcomes |
That last row is where the two ledgers collide in practice.
Stacking, bundling and double-dipping
When one project sells both a carbon credit and a nature credit on the same hectare, three arrangements are possible:
Stacking — two separate claims on different outcomes from the same activity. The buyer of the carbon credit gets the tonnes; the buyer of the nature credit gets the measured biodiversity uplift. Legitimate if the outcomes are distinct, the buyers know about each other, and the claims are not competitive. We wrote a full piece on stacking credits.
Bundling — one credit sold with both attributes attached: a "biodiversity-rich" carbon credit. The premium is real (some buyers pay extra for co-benefits), but the claim is single — the buyer gets the tonne and the story, and no one else may sell the biodiversity story again.
Double-dipping (the bad version) — selling the same habitat's recovery twice as if it were two recoveries, e.g. counting one hectare's species return toward both a nature credit claim and a regulatory "no net loss" offset for a different developer. Ecologically this is simply double counting in another currency.
Good schemes force disclosure: a registry should show, for each hectare, every claim registered against it. If a seller cannot produce the claims register, the due diligence stops there.
Where regulation is pulling the two markets together
Policy is starting to make the biodiversity ledger compulsory rather than voluntary, which changes everything. In the marine space, biodiversity net gain (BNG) policies — already required in terrestrial planning in some jurisdictions — are being designed for coastal development. Under BNG, a developer who damages habitat must demonstrate measurable net gain elsewhere, and that gain will likely be quantified in units very similar to nature credits. The policy wave is mapped in Marine Biodiversity Net Gain.
Meanwhile climate regulation (voluntary carbon market integrity rules, net-zero claim standards) is pulling carbon in the direction of stricter claim discipline. The practical effect: both ledgers are becoming more formal, more disclosures-heavy and more interlocked. A company buying a blue-carbon-labelled product in 2030 will likely be asked for both the tonnes and the condition evidence.
What buyers should ask before buying either
The questions rhyme across the two markets because the failure modes do:
For carbon credits: methodology, vintage cancer, verification body, registry serialisation, buffer contributions, Article 6 authorisation status. (Full checklist: A Buyer's Guide to Blue Carbon Credits.)
For nature credits: what exactly is the unit? Baseline method? Monitoring cadence and independence? Can you see per-hectare claims registers? What happens to the claim if the ecosystem degrades? Is there a stewardship fund for reversals, analogous to buffer pools? Who owns biodiversity rights on the site — especially where Indigenous sea country is involved (our benefit-sharing piece)?
For both: show me the full claims register for this asset. Then show me the monitoring data.
Tidewright's illustrative approach: one project, clearly-labelled outcomes
On Canopy Ledger, our fictional monitoring platform, our stance is that every restored hectare should carry an explicit outcome map: what is registered, where, under which standard, and against which claim. If a project sells stacked carbon and biodiversity units, the two should be visible on the same provenance ledger, not in adjacent marketing decks. We think most of the market's integrity problems are really disclosure problems waiting to be fixed in software.
Key takeaways
- Carbon credits certify tonnes; nature credits certify measured ecological condition or outcomes. The second unit is a constructed metric, not a physical constant.
- Nature credits will stay more local and bespoke precisely because biodiversity is place-based — global fungibility is neither achievable nor desirable for them.
- Additionality, baselines and permanence are harder in nature markets than in carbon markets; expect more bespoke contracts and longer stewardship commitments.
- Stacking is legitimate when outcomes are distinct and fully disclosed; double-dipping the same hectare's recovery under two claims is the nature-market version of double counting.
- Policy is on the move: marine biodiversity net gain rules and carbon market integrity frameworks are converging on the same formal registry infrastructure.
FAQ
Is a nature credit just a carbon credit with a different story?
No. Carbon credits have a physically-defined unit and a mature registry landscape. Nature credits certify measured ecological outcomes in units that vary by scheme; they are younger, more bespoke and not interchangeable across regions.
Can one project sell both carbon and biodiversity credits?
Yes — via transparent stacking if the outcomes are distinct and disclosed to both buyers, or via bundling if the two attributes are sold as a single, inseparable claim. Hidden stacking is a red flag.
Are nature credits verified like carbon credits?
Verification practice is less mature but analogous: a scheme-defined methodology, third-party ecological audits and a registry. The ecological auditing profession is smaller and less standardised than carbon verification, which is one reason buyers should inspect methodologies closely.
Will nature credits become as liquid as carbon credits?
Probably not, and arguably shouldn't. Liquidity in carbon rests on global tonne fungibility; biodiversity is local and its value is local. Expect a patchwork of marketplaces tied to bioregions, schemes or regulatory frameworks rather than a single global market.
How do nature credits interact with Indigenous rights?
Directly. Biodiversity outcomes often depend on and occur on Indigenous land and sea country; robust nature markets require free, prior and informed consent plus benefit-sharing frameworks before credit design begins.