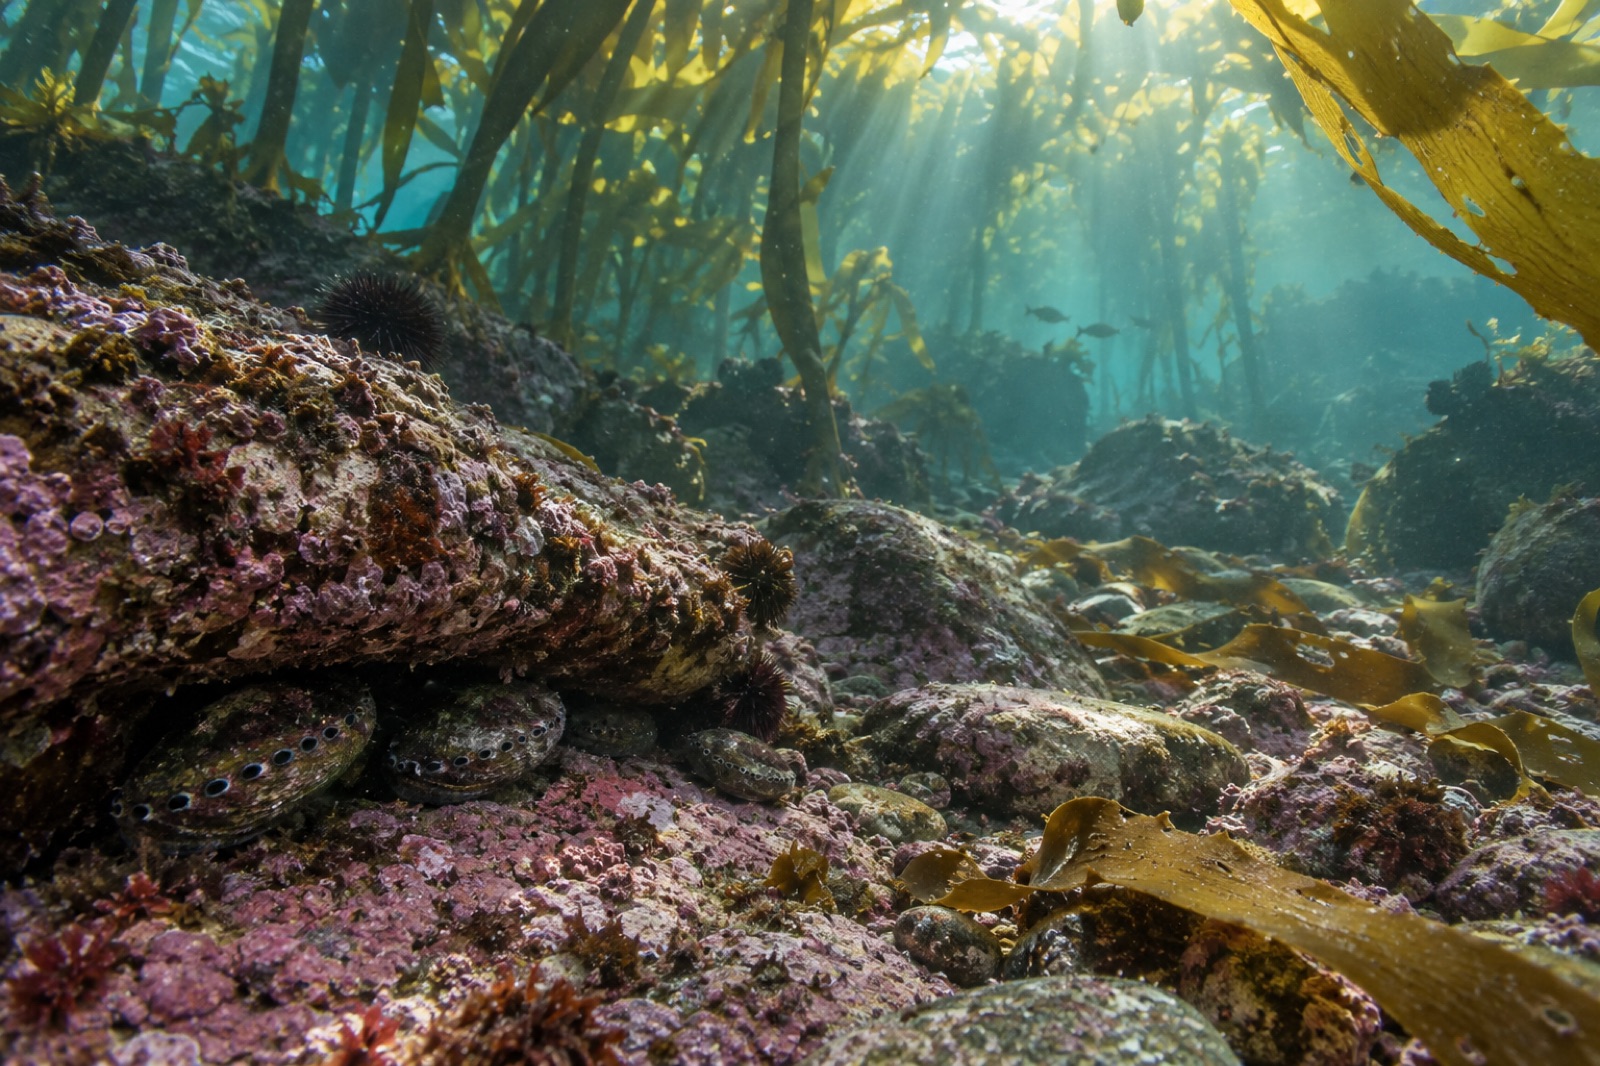
Field Notes are Tidewright's own dispatches from our (fictional) restoration sites and ledgers. Everything in this one — the credit, the buyer, the verifiers, every figure — is illustrative, written to show how we think a marine biodiversity credit should be built.
Last month, Canopy Ledger issued a biodiversity credit. Not a pilot announcement, not a memorandum, not a press-ready pledge — an issued, serialised, third-party-verified credit representing measured biodiversity uplift on five hectares of restored reef at our Lumeriah Coast program in Tasmania. It took eleven months, cost more than the credit sold for, and survived exactly none of our first-draft assumptions. This field note is the anatomy of that process, because the marine biodiversity credit market is being built right now and I would like more of the people building it to have scrubbed their metric on a dive slate rather than a whiteboard.
For the conceptual version of why these instruments exist at all — and why they are not offsets — start with our explainer on biodiversity credits. This note is about the part the explainers skip: what it actually takes to put one into the world without embarrassing yourself in five years.
The metric problem, round one
Carbon accounting starts from a comfortable fiction — a tonne of CO₂ is a tonne of CO₂ — and spends its effort on the counterfactual. Biodiversity accounting doesn't get the comfortable fiction. What is the unit of a reef coming back to life?
Our first draft answered that question the way everyone does: a composite index. Canopy persistence, species richness, eDNA community score, structural complexity, rolled into one number between zero and one, weighted by a formula I helped design and will now publicly disown. The verifier's ecology reviewer took one afternoon with it and asked the question that killed it: "In year seven, when we dispute a measurement, which part of this number do we re-measure?" A weighted composite is unfalsifiable in exactly the way a credit metric cannot afford to be. We threw it out.
What replaced it is dumber and stronger. The Lumeriah credit — our fictional unit name is the Reef Condition Class — is a pass/fail bundle of three audited thresholds, each of which a competent dive team can re-measure in a day:
- Canopy persistence: giant kelp canopy detectable on drone or satellite imagery in at least eight months of the crediting year, above a minimum mapped area per hectare.
- Recruiting community: mean fish and macro-invertebrate richness on standardised diver transects at or above 60% of the program's reference-reef benchmark — with named indicator species (among them blacklip abalone, whose slow return to the quadrats we documented in an earlier field note) required to be present.
- Grazer balance: long-spined urchin density below the program's suppression threshold on every transect in the credit block — because a canopy sitting on an urchin front is a claim about the past, not an outcome.
All three gates must pass, on the credit block, in the crediting year. One failing gate, no credit, no partial unit, no appeals. That bluntness is the entire design philosophy: the buyer should be able to understand the credit from one page, and a hostile reviewer should be able to re-run the whole audit with a dive team and a drone.
The counterfactual, round two
Everyone wants to baseline a restored barren at zero — pure crustose rock, wall-to-wall urchins — and claim all uplift as creditable. The verifier stopped us again, correctly. Reefs recover on their own sometimes; urchin fronts move; giant kelp recruits in good years even without help. A counterfactual of "permanent zero" is flattering fiction.
So the credit's uplift threshold is net of a control-block trajectory: four matched reefs outside the program boundary, surveyed on the same calendar with the same methods. Natural recovery on the controls gets subtracted. In the crediting year (all numbers illustrative), the credit block passed its three gates with margins ranging from modest to comfortable, while the control blocks trended up in richness but passed no gate — the difference we credit to five years of Holdfast line seeding and urchin suppression. We also took a further 20% conservative discount off the issuance volume for measurement uncertainty, because the honest answer to "how sure are you?" is "not sure enough to sell the last fifth."
I want to be plain that this is the direction the whole field should travel: credits sized by measured outcome minus natural recovery minus uncertainty. Anything simpler is marketing.
Verification week
The third-party audit ran as a field verification, not a document review, which was our choice and our ordeal. The verifier's team — an eDNA lab, an audit diver, and a chain-of-custody specialist who I suspect moonlights as a prosecutor — spent five days on the coast. Three moments from that week will stay in our institutional memory:
- They rejected our weather logic. eDNA survey results from a storm week showed a richness spike that flattered the block — storm-driven material washing in from elsewhere. We argued climatological averages; they argued the sample was what it was. We re-sampled. The re-sample still passed, and is now in the registry packet.
- They transected the block boundary on purpose. Auditors love edges; biodiversity near a boundary can be borrowed from the un-credited reef next door. We had designed the block with hard edges on a map, not soft edges in the water. Buffer zones of thirty metres inside every boundary are now standard in our credit design.
- They made us fail something. One transect in one sub-block failed the urchin gate on the final count. We could have argued; instead we severed the sub-block from the issuance and seeded it harder. The credit shrank; the credit meant more. This is what "verification" is for.
Who bought it, and what it sits next to
The buyer is a fictional Tasmanian food company with cold-chain operations two hours from the reef, meeting a voluntary nature-positive commitment — a contribution claim, not an offset, in line with the principles we laid out in our piece on stacking carbon and biodiversity credits. The same Lumeriah hectares already generate canopy-attendance data that may, years from now, underpin blue-carbon claims; the two instruments describe different things the reef does, and the registry entries are written so they cannot be conflated.
The money matters less than the architecture: proceeds flow to the program's monitoring budget first — credits that pay for their own measurement are credits that can keep existing — and to the program partnership under its agreed benefit-sharing split. The sale price more or less covered one year of the credit block's monitoring. That is not an impressive business. It is, however, the first closed loop: a buyer paid for a verified ecological outcome, and the payment funds the next round of verifying. The loop is the point.
What we would do differently
Honestly? Start smaller. We tried to issue a credit that demonstrated the whole framework at once, and the framework's education cost landed inside one transaction. The next issuance — same metric, larger block, Mendocino program — has a head start because the Lumeriah credit exists as a worked example a verifier can copy. And I would budget the verifier's time like capital, not like an expense: the two best engineering decisions in this whole process were made by people paid to tell us no.
Eleven months, one metric in the bin, one severed sub-block, and a credit small enough to fit on an index card. It is the most important financial instrument I have ever worked on.
Key takeaways
- Tidewright's (fictional) first biodiversity credit is a pass/fail bundle — canopy persistence, recruiting community, grazer balance — designed so an auditor can re-measure every component in a single field day, after a weighted composite index proved unfalsifiable in review.
- Creditable uplift is measured net of matched control reefs, with a further 20% uncertainty discount: natural recovery and measurement doubt are subtracted before anything is sold.
- Field verification — including rejected storm-week eDNA, boundary audits, and a severed failing sub-block — shrank the credit and strengthened it. Verification should be treated as engineering input, not overhead.
- Proceeds flow first to the monitoring budget under the program's benefit-sharing split; this first sale funded roughly a year of the credit block's own verification. All figures are illustrative.
- The metric, registry structure and worked transaction now serve as the template for the next planned issuance at the Mendocino program.
FAQ
Is this a real, purchasable credit?
Tidewright is a fictional company, and the credit described here is fictional — an illustrative account of how we believe marine biodiversity credits should be designed. Real biodiversity credit pilots do exist globally, and the design principles here (measurable outcomes, baselines, independent verification) reflect genuine practice in that emerging field.
How is a biodiversity credit different from a carbon credit on the same reef?
They measure different outcomes. A carbon credit quantifies CO₂-equivalents stored or avoided; a biodiversity credit quantifies audited ecological condition. The same hectare can underpin both, provided the registry records them as separate claims on separate attributes — the conflation of the two is a double-counting risk we cover in our credit stacking explainer.
Why pass/fail gates instead of a single biodiversity score?
Because credits outlive the people who designed their metrics. A weighted index is easy to compute and nearly impossible to audit a decade later; a small set of re-measurable thresholds — canopy months, richness against a reference benchmark, urchin density — can be checked by any competent team with standard methods, which is what makes the claim durable.
Who verified the credit?
In this fictional account, an independent third-party audit team: an eDNA laboratory, an audit diver and a documentation specialist, applying the metric on site rather than reviewing paperwork. Independent field verification is the standard we argue for across the sector — the verifier must be able to say no, and to be believed when they do.